
INSIGHTS
R&D credits beyond software companies
August 7, 2025
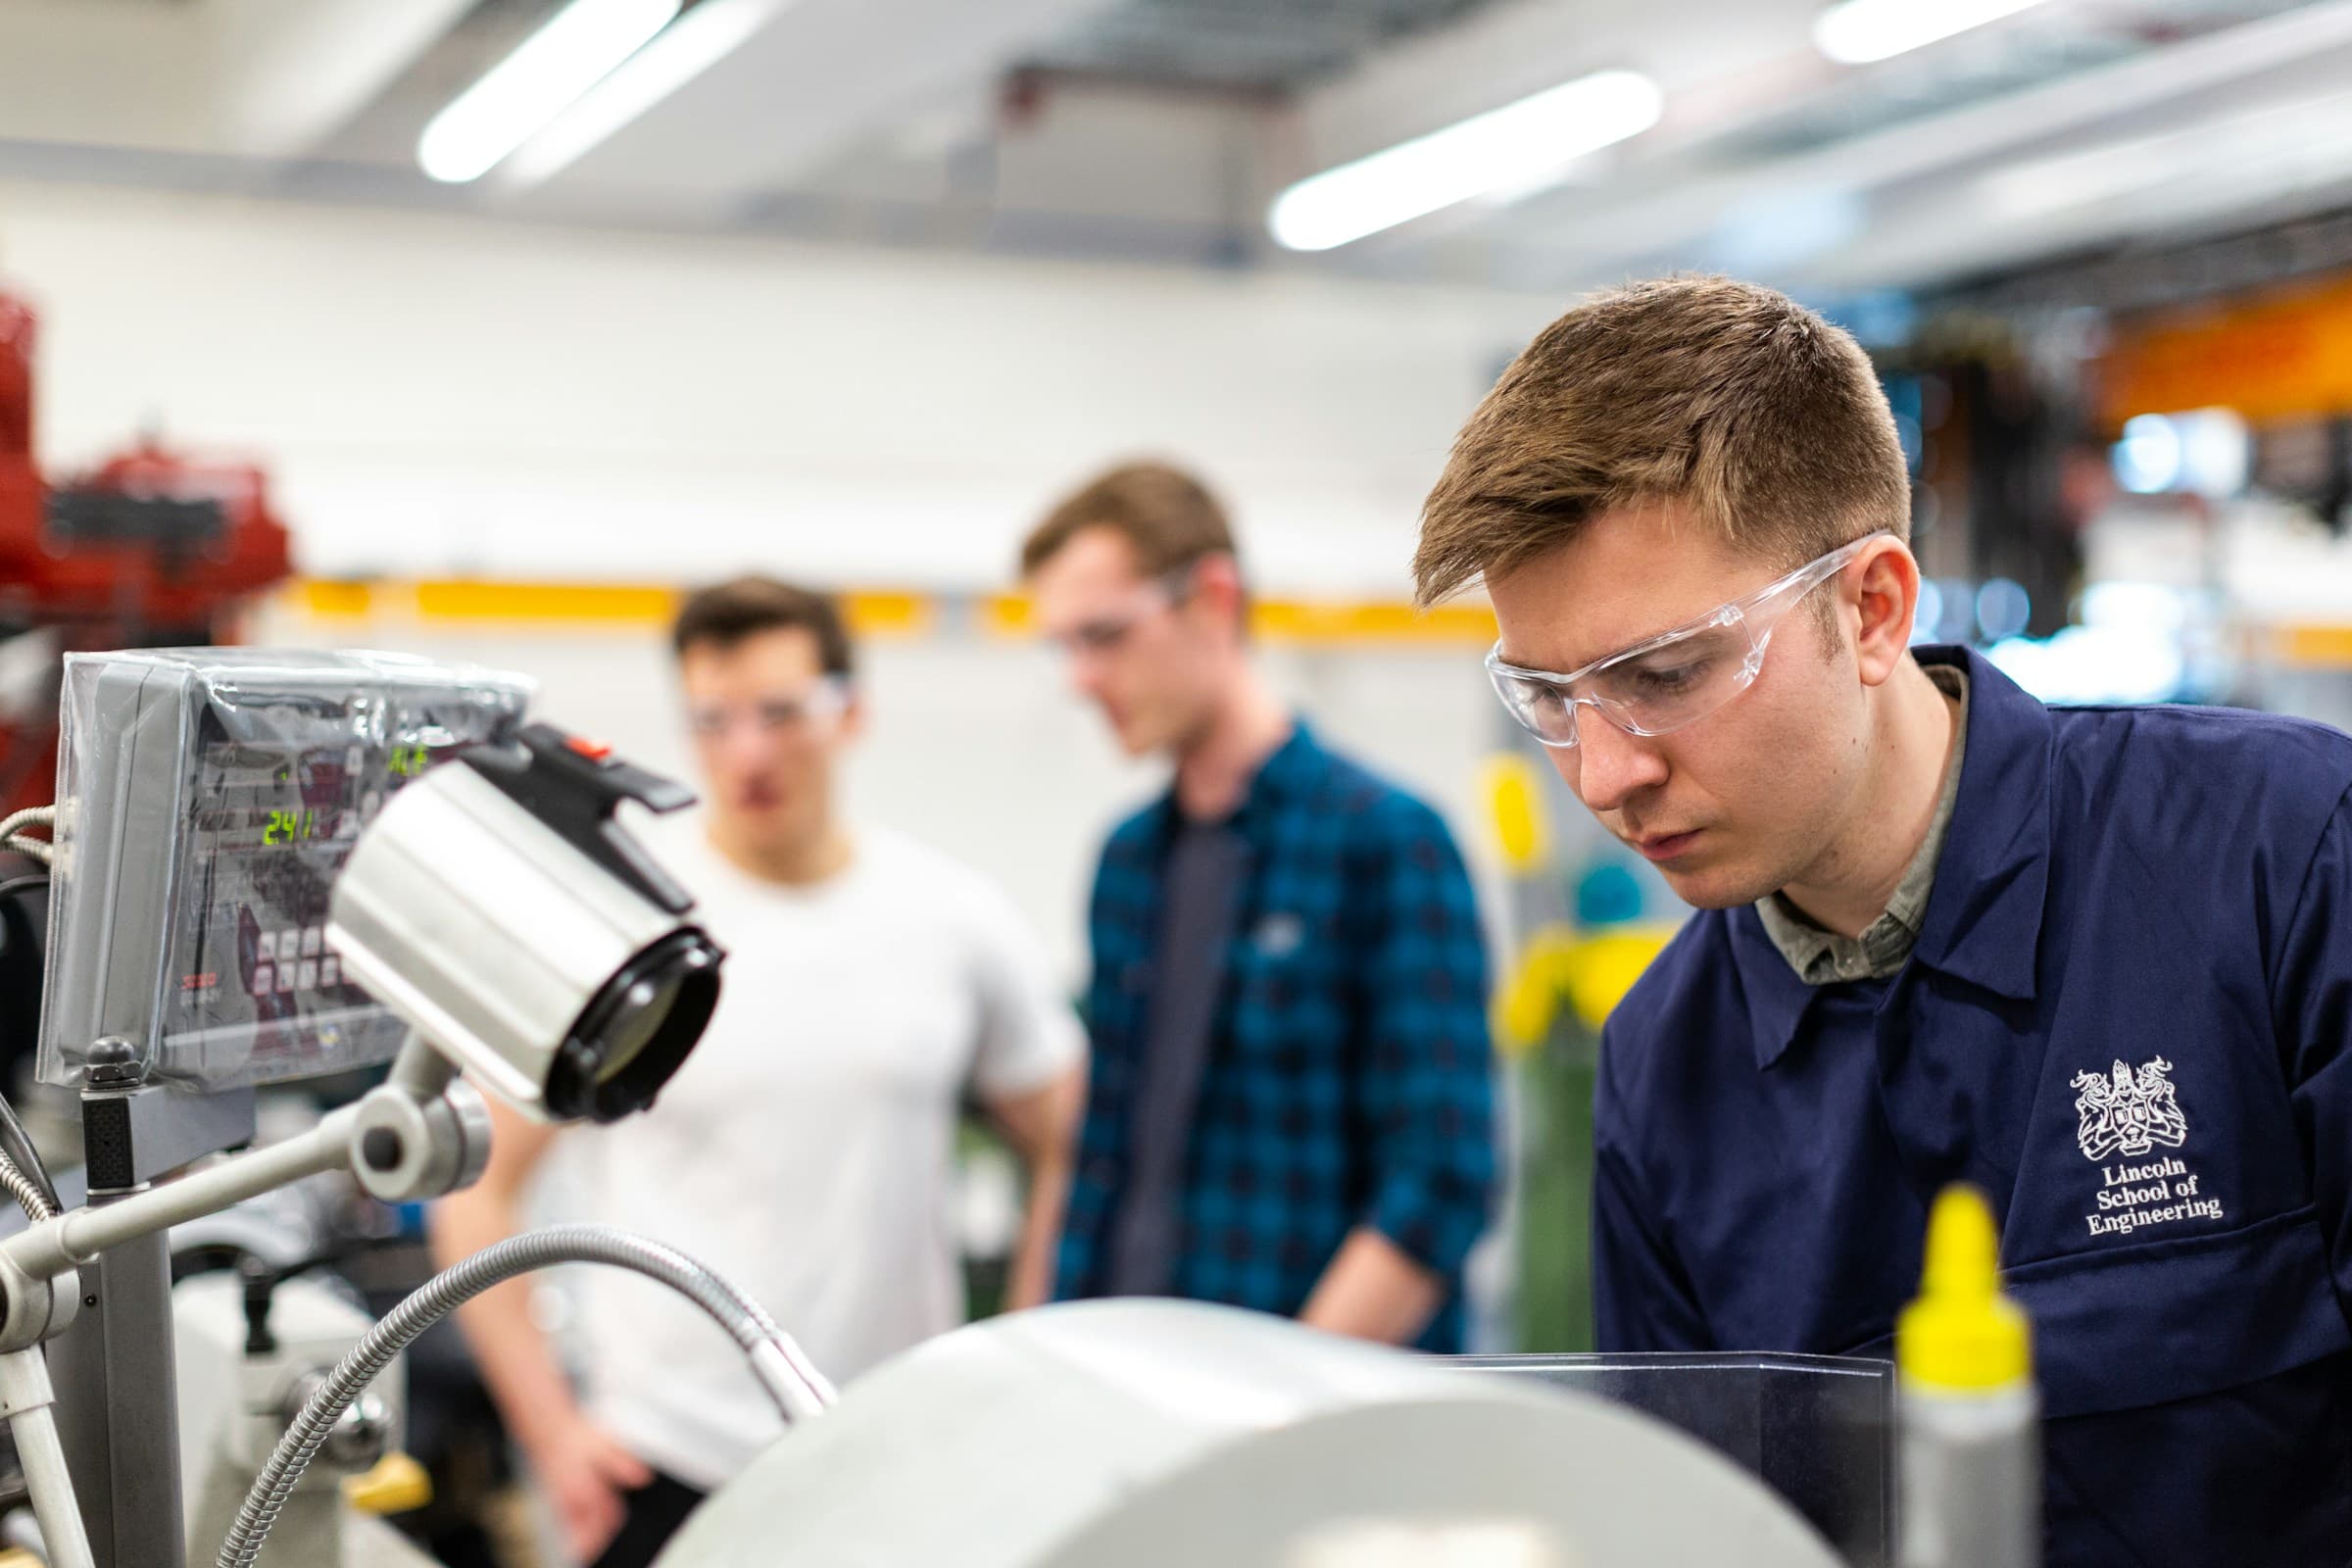
The R&D credit is often associated with software and life sciences, but the tax code does not limit it to any industry. It applies to qualified research, and many manufacturers, food producers, consumer product companies, and engineering firms do that work as part of normal operations.
What qualifies outside software
The same four-part test applies in every industry. The work must aim to improve function, performance, reliability, or quality; rely on engineering or the sciences; address technical uncertainty; and involve a process of evaluating alternatives. Examples that often qualify:
- Designing new products or improving existing ones, including prototypes and pilot models.
- Developing or improving manufacturing processes to raise yield, reduce scrap, or increase throughput.
- Designing tooling, fixtures, molds, and automated equipment.
- Developing food, beverage, or cosmetic formulations and testing shelf life or stability.
- Engineering packaging to meet strength, sustainability, or cost goals.
- Testing new materials or components against technical specifications.
When a full product does not qualify, the rules allow the analysis to shrink back to the specific component or subprocess that does.
What does not qualify
- Routine quality control testing and inspection.
- Work after a product or process begins commercial production, unless it resolves new technical uncertainty.
- Adapting an existing product to a customer's requirements without new technical uncertainty.
- Research funded by a customer, where the company is paid regardless of outcome or does not keep substantial rights.
Costs that count
Qualified costs include wages for engineers, technicians, and production staff for the time they spend on qualified work, supplies consumed in experimentation, such as materials used in trial runs, and 65% of payments to U.S. contractors performing qualified research on the company's behalf. Depreciable equipment does not count.
Why it matters now
Domestic research costs can again be deducted in the year incurred for tax years beginning after 2024, and smaller companies may be able to apply that treatment to 2022 through 2024. Combined with state credits, including the revised Texas credit, the total benefit for a company with an active engineering or product team can be meaningful.
Vallou prepares R&D credit studies for manufacturers, food and beverage producers, and consumer product companies, with CPA review of every study.
Sources
- Internal Revenue Code §41(b) and §41(d), qualified research expenses and qualified research.
- Treas. Reg. §1.41-4, including the shrinking-back rule in §1.41-4(b)(2).
- Internal Revenue Code §41(d)(4)(A), (B), and (H), research after commercial production, adaptation, and funded research.
- Treas. Reg. §1.41-4A(d), funded research.
- Internal Revenue Code §174A, as added by Public Law 119-21.
Have questions about how this applies to your business?
This information is provided for general informational purposes only and does not constitute tax, accounting, or legal advice.